Income Protection vs Critical Illness Insurance

Ready to look at a price?
See what income protection costs for you, then decide.
Income protection insurance creates financial security by replacing a proportion of your income if you’re unable to work through illness or injury. It enables you to meet your living expenses and maintain your standard of living while you focus on recovery. It’s a versatile option for all kinds of people, from individuals and couples to family breadwinners and the self-employed.
Income protection and critical illness insurance are designed for two distinct purposes. Both are intended to help you with the financial impact of being unable to work because of health conditions but the situations in which you can make a claim and the way in which your benefit is paid out are different.
Their purposes are different, but critical illness and income protection policies have several features in common.
Purpose: Both types give you financial support when you’re unable to work because of poor health.
Tax: If you pay the premiums for your own critical illness and income protection insurance, you won’t have to pay tax on the benefit you receive.
Premiums: What you pay for your policy is influenced by your age, health, lifestyle, and the level of cover you want. This is part of what’s called ‘underwriting’.
Exclusions: Neither will cover you for specific things like pre-existing health conditions and certain kinds of activity.
Information: When you apply and also when you claim, you need to give complete and accurate information about your health and lifestyle.
Customisable: Policies are flexible enough for you to tailor them to your individual circumstances.
Peace of mind: Both types give you not only financial security but also peace of mind.
Claiming: To receive the benefit you need to go through a claims process, which will include giving evidence of your health condition, such as confirmation from a qualified medical professional.
Despite the similarities, there are several areas in which the two types of insurance differ.
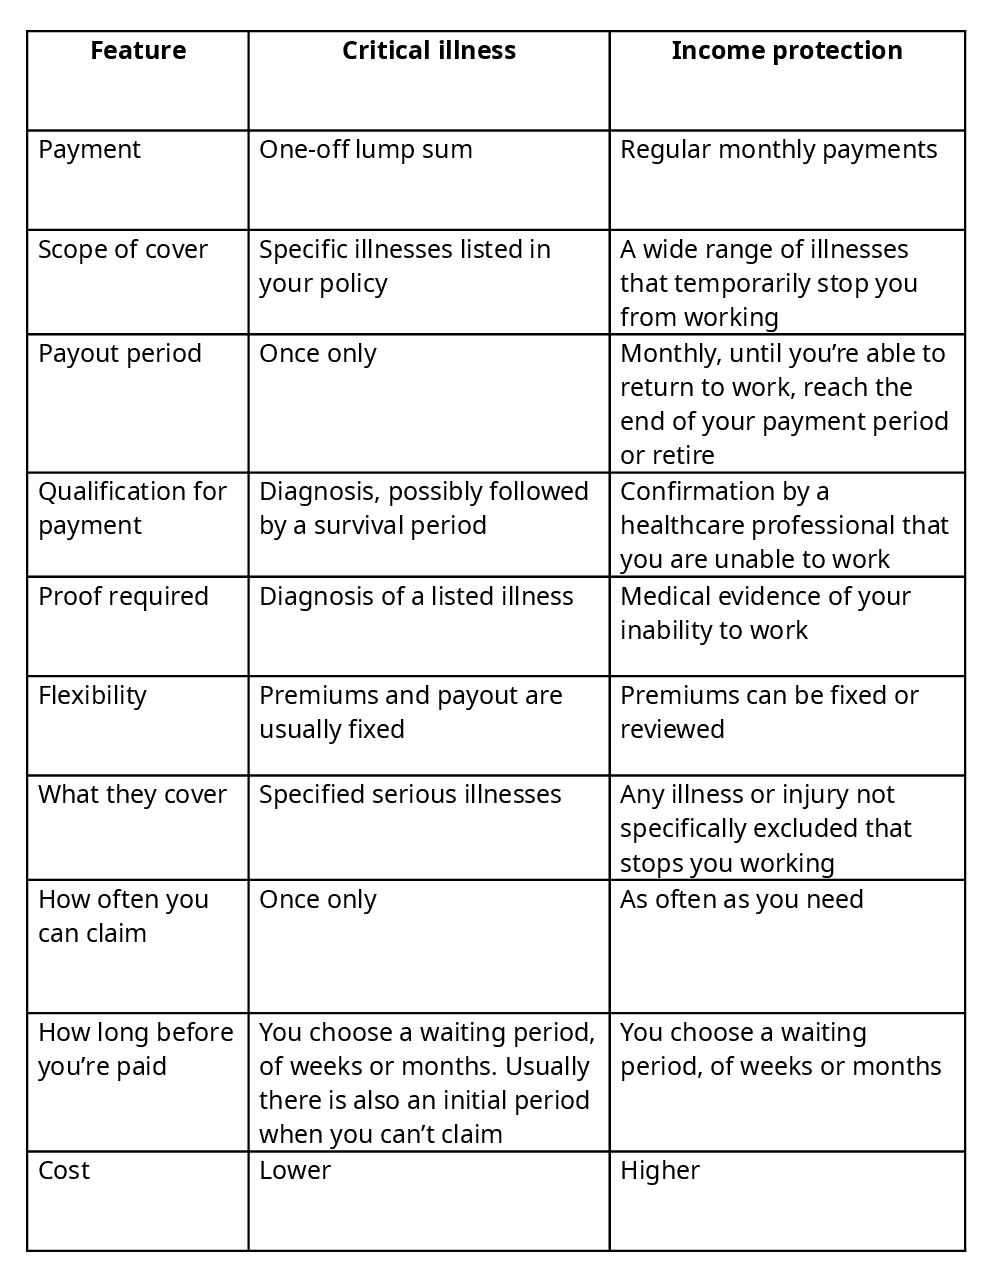
Since the two types of insurance solve distinctly different problems, the question of which is best isn’t really possible to answer in binary terms. Rather the question should be, ‘which one suits you best?’
Income protection insurance could be a good choice if:
Your main concern is how you’d manage should illness or injury temporarily stop you from working
You’d like regular monthly payments to replace a proportion of your income
You want to be able to claim whenever it happens during your working life
Critical illness insurance may be a good fit if:
You worry that a serious illness could permanently stop you from working
A lump sum payment would give you the flexibility to cover your expenses and look after your family.
If you want to be covered for both eventualities then there’s no reason not to take out both types of insurance. Obviously, the cost of two policies is considerably more than one, so you’d want to balance the range and level of your cover with what you can afford.
Critical illness insurance covers the kind of serious medical problems that can be described as life-changing or life-limiting. Coverage differs under different policies, but the core conditions include cancer, heart disease, strokes and major organ transplants.
Together, critical illness and income protection insurance give you comprehensive financial protection for illnesses and injuries that can have a serious impact on your ability to earn. While income protection gives you short-term support until you’re able to go back to work, critical illness is there to provide a safety net if an illness means you’re unlikely to be able to work again.
They are separate policies which you can take out independently of each other with different insurers, but most companies that offer one will offer both, so you may feel it’s easier to take out two policies with one insurer. The choice is entirely up to you.
Illness and injury are among the most frequent causes of lost income. There is some financial support available, both from employers, who are legally obliged to provide statutory sick pay, and from the government in the form of benefits for the self-employed and in some cases of disability. However, the amounts you’re entitled from any of these sources may fall short of what you really need to maintain your lifestyle or even makes ends meet. Critical illness and income protection insurance enable you to make financial arrangements that genuinely answer your needs and give you the security and peace of mind that comes with knowing you and your dependants are prepared for the monetary consequences of both short-term and long-term inability to work.
Income protection UK
If you can't work, your income can.
Income Protection vs Critical Illness Insurance
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.
Income protection for smokers
If you smoke, you may have a tough time getting income protection insurance, but it’s not impossible.