What does income protection cover?

Contents
According to a 2022 report, 9 million people in the UK had no savings and another 5 million had less than £100. A Bank of England report in 2024 found that 34% of adults have less than £1,000 saved and 65% believe they couldn’t last for three months without resorting to loans. For 33%, one month would be a struggle.
There’s more than one way to lose your income. Redundancy, dismissal and pay cuts are all genuine risks, but the most common cause of income loss is an inability to work, as the result of illness or injury. In the four months up to April 2024, 98,000 jobs were lost through redundancy. Meanwhile, in April, the number of people off work because of long-term sickness reached a record peak of 2.8 million.
Financial support and peace of mind
Income protection addresses both practical and emotional needs:
It provides a financial safety net that helps people pay their bills and maintain their lifestyles if illness or injury stops them from working.
It also gives them the permanent peace of mind that comes with knowing they have a safety net in place.
Financial support
Income protection policies are based on a largely universal model. Policyholders choose:
- how much they would need to replace their income each month (benefit amount);
- how soon after stopping work they want to start receiving it (waiting period);
- how long they believe they might need it for (benefit period);
- and how much they’re willing or able to pay for it (monthly premium).
The monthly benefit amount they can receive is a proportion of their gross salary, usually up to 65%. This roughly mirrors what they would take home after tax and NI. Most policies also put a cap on the monthly total.
If the cost of getting the maximum cover is too high, policyholders can make various adjustments to reduce the premiums they pay. A lower benefit amount, shorter benefit period or longer waiting period are all options.
With millions of people currently unable to work because of long-term sickness (longer than 4 weeks), income protection is more important than ever. You buy a policy while you’re healthy and working, either self-employed or as an employee. If you come down with an illness or suffer an injury that forces you to stop working, you can make a claim and, once it’s approved, you’ll start receiving your monthly benefit payments.
What illnesses does income protection cover?
The important point to remember about income protection is that it doesn’t cover you for specified illnesses or injuries. It is based on the principle that if a health condition stops you from doing your job, your insurance should support you. You do need a healthcare professional to confirm that your condition prevents you from working and sometimes your insurer will ask for supplementary information, but if those requirements are met your policy should pay out as you expect.
Bear in mind that policies will usually specify circumstances in which your claim will be unsuccessful, but the average approval rate for the top 5 companies its 95.6%. Later, we’ll cover the kinds of exclusions you can expect to find in most policies.
Does income protection cover mental illness?
The short answer is yes, because illness and injury are not always physical. Income protection policies recognise this by covering you for mental ill-health problems that can be just as debilitating for working people as bodily conditions. In fact, poor mental health is one of the three most common reasons for claims, along with musculoskeletal injuries and cancer.
The principle is the same as for physical conditions: if you can show that it stops you from working it should pay out, subject to the common restrictions we’ll look at it in a moment.
Looking for cover?
Find out what protection Eleos can give you
Tax can be an issue in insurance, both when the premiums are paid and when you receive money under a claim.
Tax on premiums
If you pay the premiums for your policy you won’t be taxed, but if your employer pays for your insurance then the premiums can be treated as a taxable benefit, just like a company car. Some employers may pay the tax on your behalf, but it’s worth checking.
Tax on pay-outs
The vast majority of insurance payouts are tax-free. There are a few exceptions, such as the savings or investment element of a life insurance policy, but any money you receive from an income protection won’t be taxed.
A question that’s frequently asked is ‘Does income protection cover redundancy?’ As we’ve already explained, income protection won’t cover you if you’re dismissed on valid grounds, your job is made redundant or you resign. Its only purpose is to insure your income if illness or injury prevents you from working.
Redundancy insurance, sometimes called unemployment income protection, is available from some insurers. It does cover you for involuntary redundancy but not if you’re dismissed, take voluntary redundancy or resign.
It’s worth mentioning that there are three types of cover relating to your inability to work.
Own occupation
This covers you if you’re unable to carry out the duties of your normal job and is therefore the easiest to claim.
Suited occupation
If you’re able to switch to another job that suits your abilities and experience you may not be able to claim. If no suited occupation is available then your claim should be successful.
Any occupation
If your employer can keep you on in any job this level of cover won’t pay you. In order to claim you have to be unable to perform any available role as an employee.
Long-term and critical illness
Income protection is a relatively short-term financial solution. Although some policies will pay you for up to a maximum of 5 years while you’re unable to work, periods of 1 and 2 years are more common. If you contract a critical illness that may be incurable or even in extreme cases terminal, critical illness insurance is much more appropriate. Income protection and critical illness cover serve very different purposes although you’ll often find insurers offering critical cover as an add-on to income protection.
What’s excluded from your cover
Some health conditions that stop you from working won’t be covered by income protection insurance. These are called exclusions. They won’t stop you from getting insurance, but you need to be aware that you won’t be able to claim for them. They fall into three broad groups:
Conditions that are not considered to be ill-health
Does income protection cover maternity leave? No, neither can you make a claim if you take time off work as a result of a normal pregnancy without complications.
Illnesses or injuries caused by activities that the policy expressly excludes
These include anything caused by prohibited behaviour such as drug and alcohol abuse or self-inflicted injuries, including complications from non-essential surgery. In addition, policies will exclude the consequences of dangerous activities like extreme sports, mountaineering and skydiving.
Conditions that you had at the time of taking out the policy or in the recent past
These are referred to as pre-existing conditions. For example if you’re already suffering from cancer, diabetes or depression when you take out your policy you must tell the insurer. You won’t be able to claim if the condition stops you working, but even more importantly, if you keep this information from your insurer it could invalidate your entire policy.
Many insurers will also look at your and your family’s medical history to see if there’s a risk of a past condition returning or a future one developing. They’ll judge whether that particular condition will be excluded from your cover. As with existing conditions, you must tell the insurer about everything you know about your and your family’s history.
Waiting periods
There’s a fourth category, which arises from the way income protection policies work. When you take them out you are asked to choose a waiting period, which is the time you are happy to wait between making your claim and receiving your first payment (perhaps because you have employee sick pay or adequate savings, for example). If you suffer an illness or injury from which you recover before the end of your chosen waiting period your claim won’t be paid.
Unlimited claims
Your policy will remain in force for as long as you keep up the premium payments. You’re able to make as many claims as you need to during the life of your policy.
Related claims
Sometimes you may make a successful claim, receive payments and then recover enough to return to work. Your claim ends. If the same condition recurs you can make what’s called a related claim but you usually need to have been back at work for a specified minimum period before you can do so.
Customisation
General insurance policies like buildings and car insurance give you very few options to tailor the policy to your budget. The amount of cover required is largely out of your hands.
Income protection is different. Although it’s related to your income and subject to an upper limit for monthly payments, within those restrictions you have a great deal of choice in how you design your cover. The ability to customise your policy is very helpful for your budgeting.
Extras for policyholders
Insurers are naturally in competition for your business. This means that they monitor the market and their competitors so they can offer the best value possible.
Competition has also prompted insurers to offer free extras like exclusive services and money-saving offers. These don’t usually form part of your contract with the insurer and they’re often called ‘discretionary’ because the insurer can’t guarantee they’ll always be available. However, they are offered as a promise and it would reflect very badly on an insurer if they failed to honour their promises.
For example, Eleos currently gives its policyholders these extras:
• Cashback on all purchases from a long list of top consumer brands
• A 24/7 remote GP service
What does income protection cover?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
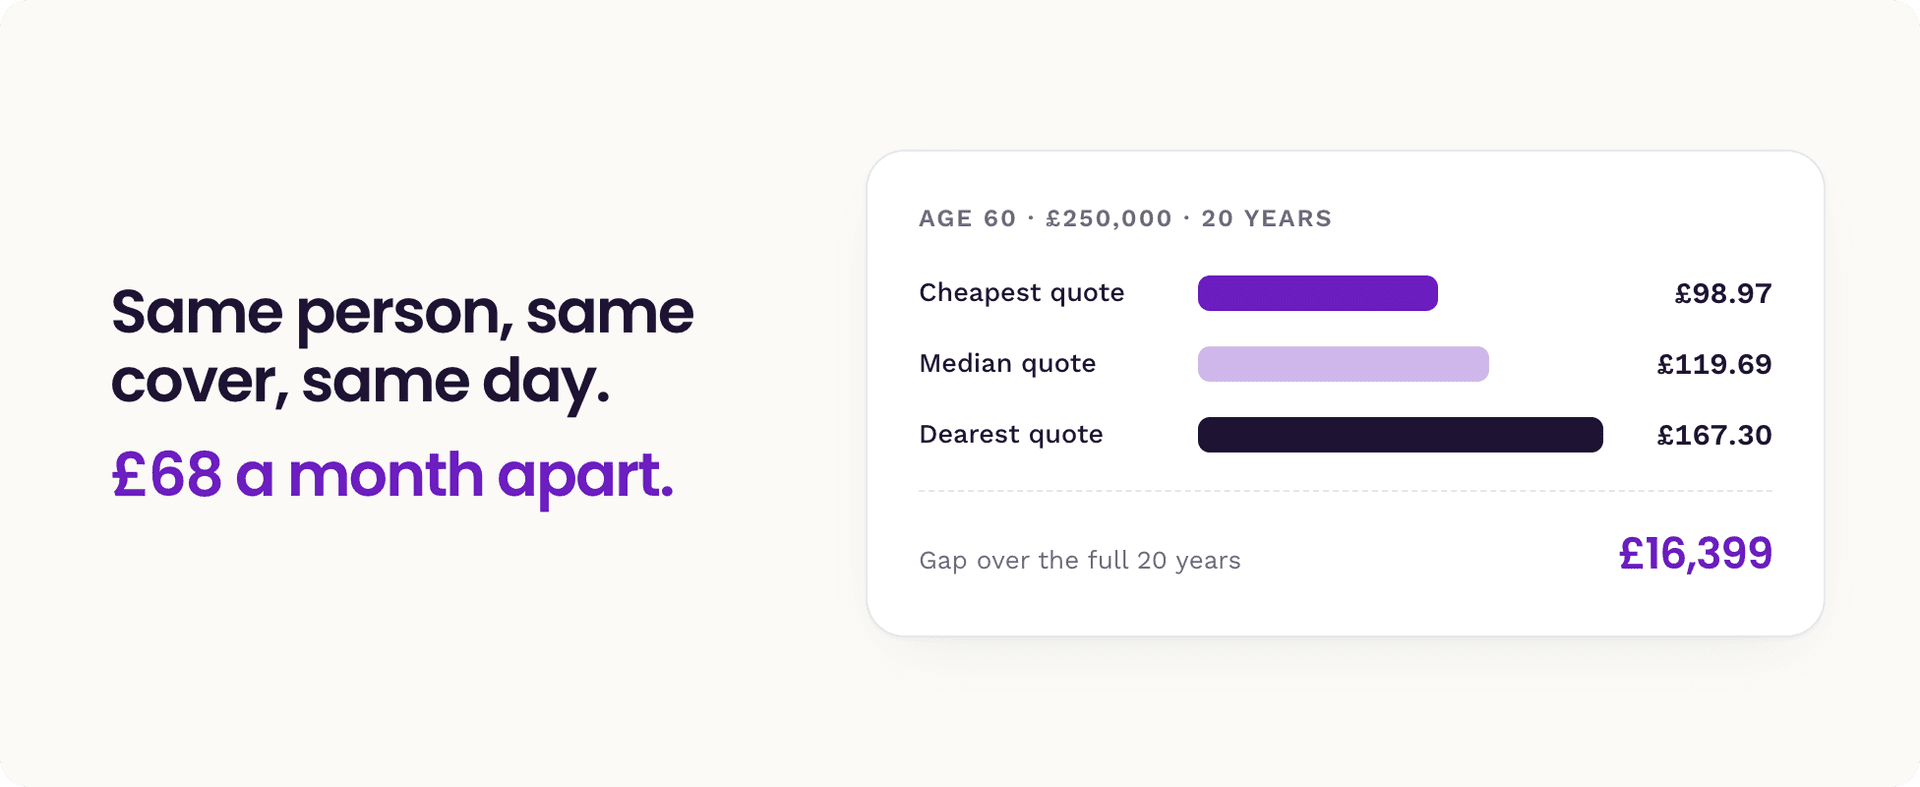
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.