Level term vs decreasing term life insurance

Contents
Term life and whole life policies are fundamentally different. Whole life policies have no fixed end date and continue in place until the insured passes away, whenever that may be. Term life insurance policies have an expiry date that’s fixed from the start. If the insured is still living when the policy reaches that date, their cover comes to an end.
This type of policy is taken out to insure the life of the policyholder, or in some circumstances a third party, for a fixed number of years. What makes it ‘level’ is that the sum payable on the death of the insured is set when the policy is taken out and remains the same for the duration.
So how does level term life insurance work? Level term policies can last for anything from 5 to 40 years, although depending on the age of the insured at the start of the policy it may be possible to exceed 40 years. The monthly premiums often stay the same throughout the life of the policy, but it’s not uncommon for them to be reviewed upwards as the insured grows older and possibly experiences a decline in health. If the premiums do increase, the sum insured will not. The rising cost is merely a consequence of the increasing risk.
As its name suggests, decreasing term life insurance runs for a fixed period and the sum insured is reduced over the life of the policy. At the end of the fixed term the cover ends. Although the payout decreases, the premiums usually stay the same throughout, but they also tend to be lower than for some other types of term policy. This is because the risk to the insurer decreases over time, making it less expensive for them to provide cover.
Purpose
Level term policies are typically chosen by people who want to combine the certainty of future financial security for their families with consistent, affordable premiums. They can work well for people who only feel the need to support their loved ones for a finite period – perhaps until their children have grown up and established themselves in the adult world.
Decreasing term policies are mostly chosen by people who have some form of long-term debt, as a means of ensuring it’s repaid should they pass away. It’s particularly suitable for mortgages, where the sum owed to the lender decreases over the years until it’s paid off. A decreasing term life policy can be arranged to run concurrently with the mortgage so that, if the insured should die at any point, there will be sufficient funds from the policy to pay off what remains of the mortgage debt. Once the policy reaches its fixed expiry date, cover will end.
Cost
The premiums for level term policies usually remain the same although, as already mentioned, the insurer may have the right to increase premiums if the insured’s health deteriorates significantly. The premiums for decreasing term policies also remain the same but they are calculated at a lower level because of the diminishing risk to the insurer.
Simplicity
Both level and decreasing policies are relatively simple and straightforward. The final payout, whether fixed or decreasing, is calculated at the start so you know what you’re getting. In most cases the premiums won’t change so you have certainty throughout. Where it can become more complicated is if your circumstances change and you wish to extend either. If your insurer agrees to your request, they’re likely to increase your premiums and you may also have to undergo some form of additional underwriting to reassess the new level of risk.
Disadvantages
The main drawback with level term insurance is that it can’t keep pace with inflation. Over a period of several years the true value of the fixed payout will be eroded, even if the inflation rate remains low as it did from 2012 until 2021. Let’s as an example a sum insured of £200,000 taken out in 1999. Using the Bank of England’s inflation calculator, that sum should now be over £370,000. If the policy paid out today it would have lost 46% of its value.
With decreasing term life insurance, the main drawback is built into its design – it may adequately cover a debt such as a mortgage but it’s unlikely to provide any extra funds for your family’s other costs.
The key differences at a glance
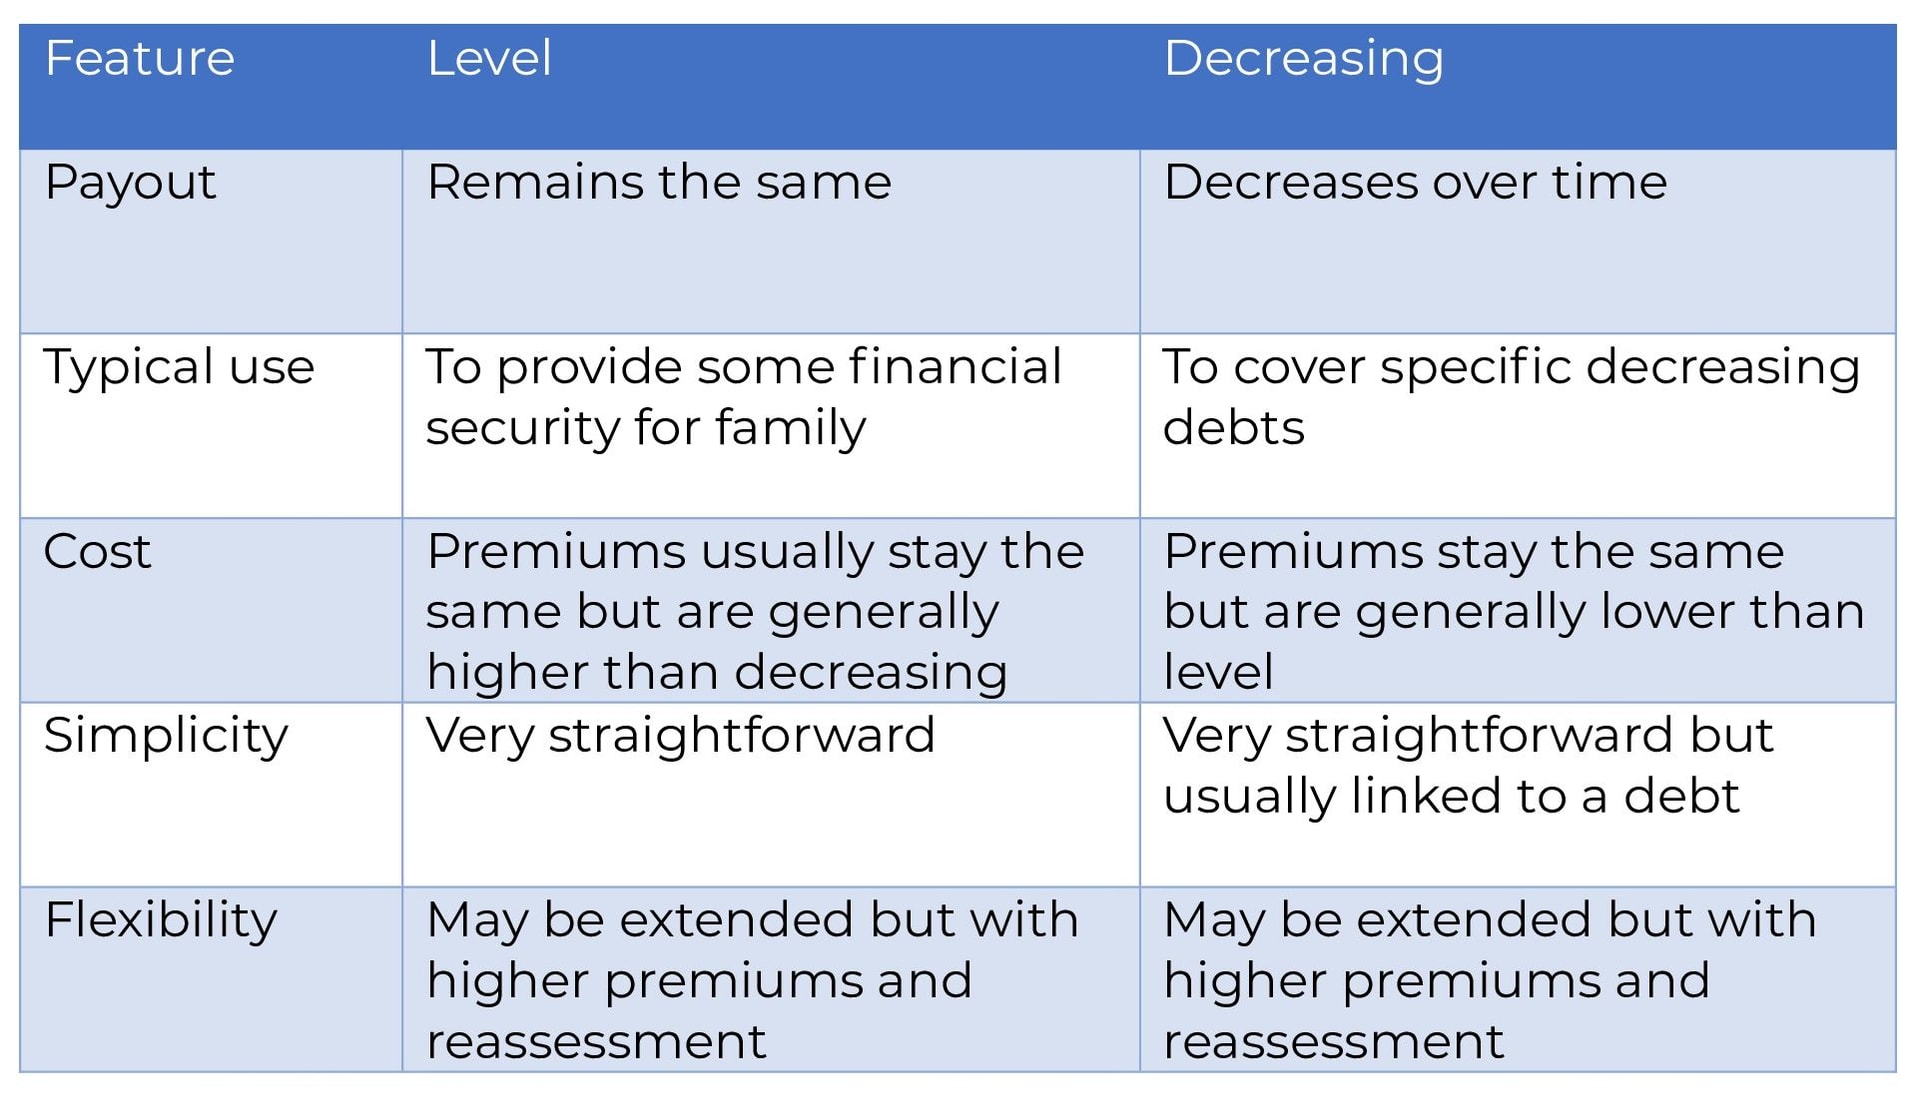
As you can see, it’s a little like trying to compare apples and bananas. The real question is, what do you need your life insurance for? Decreasing term may be ideal for the needs of one person and completely unsuitable for those of someone else.
Switching from one to the other
If your circumstances change during the life of your policy, you may find that it no longer fulfils its purpose and you’d like to convert your cover into the other kind. This is not usually a case of simply switching from level to decreasing or vice versa. More likely it will involve taking out a new policy, which will mean a fresh application and underwriting process. Once you’ve got your new policy you can cancel the old one but turning your existing policy into a different one isn’t really an option. It may be a good idea to take professional advice.
You can have as many life insurance policies as you like and there’s no reason not to have both level and decreasing simultaneously, although the cost of two will naturally be greater than one. There are two ways of doing this.
Hybrid policies
Some insurers offer policies that combine elements of both. You would take out a policy which essentially provides two strands of cover – level and decreasing – usually paid for with a single premium. There may be cost-efficiencies in arranging this with a single insurer, which would keep it simple.
Separate policies
Alternatively, you can take out separate policies, either with one insurer for both or different insurers for each. This is likely to give you more opportunities to customise the policies so they will more closely meet your needs, although it may be more expensive than the hybrid option.
If your circumstances change during the life of your policy, you may find that it no longer fulfils its purpose and you’d like to convert your cover into the other kind. This is not usually a case of simply switching from level to decreasing or vice versa. More likely it will involve taking out a new policy, which will mean a fresh application and underwriting process. Once you’ve got your new policy you can cancel the old one but turning your existing policy into a different one isn’t really an option.
Is level term or decreasing life insurance better?
As you can see, it’s a little like trying to compare apples and bananas. The real question is, what do you need your life insurance for? Decreasing term may be ideal for one person’s needs and completely unsuitable for another’s.
What each one actually costs
We priced both types across 336 combinations of age, cover amount and policy length in September 2026, using live quotes from UK insurers. Decreasing cover came out cheaper every time, and the gap grew with age: around 16% cheaper at 25, 26% at 35 and 45% at 60. The full figures are in what life insurance really costs in the UK.
Level term vs decreasing term life insurance
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
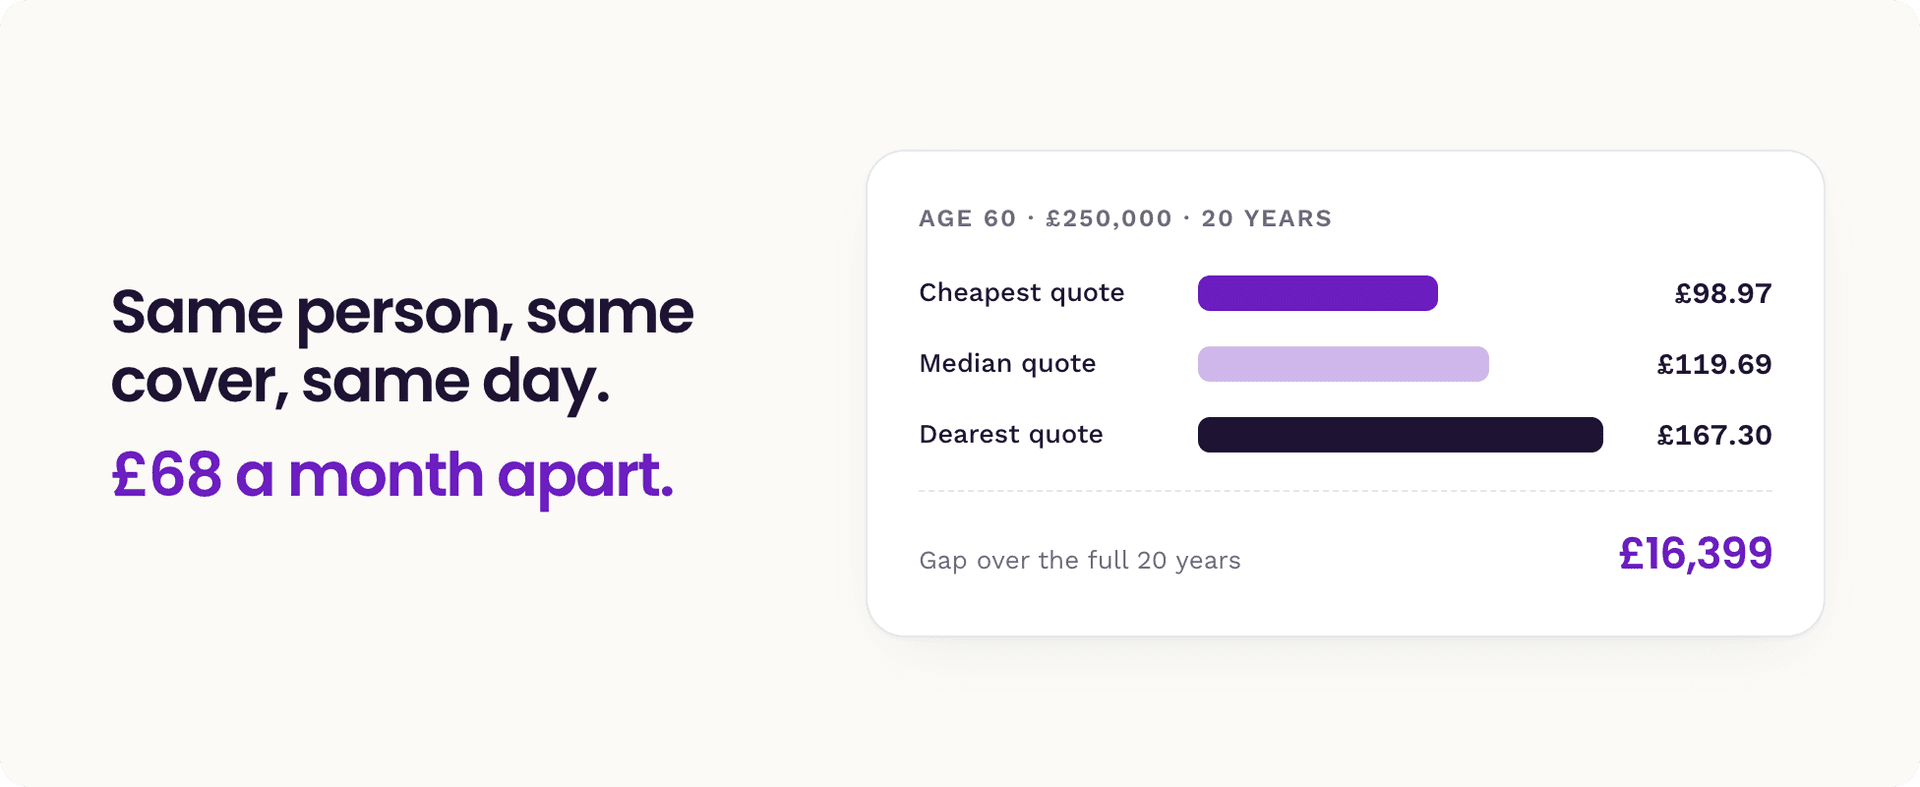
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.